Independent Loss Adjusters (ILA) may be worth speaking to when a property insurance claim needs more explanation or administration than you can comfortably manage. That could involve an unclear repair allowance, a disputed decision or a claim with several specialists involved.
Appointing support is a choice. It should depend on the help you need, the proposed service and its cost. A straightforward claim may be manageable directly with your insurer.
Understand Who Is Representing You
An insurer may appoint a loss adjuster to investigate a claim on its behalf. A policyholder can separately appoint a representative to help present and discuss their own claim. These appointments serve different parties.
ILA’s explanation of its service describes its policyholder-focused role. Independent Loss Adjusters Ltd is authorised and regulated by the Financial Conduct Authority for insurance distribution activities. Regulatory status does not guarantee a particular claim result.
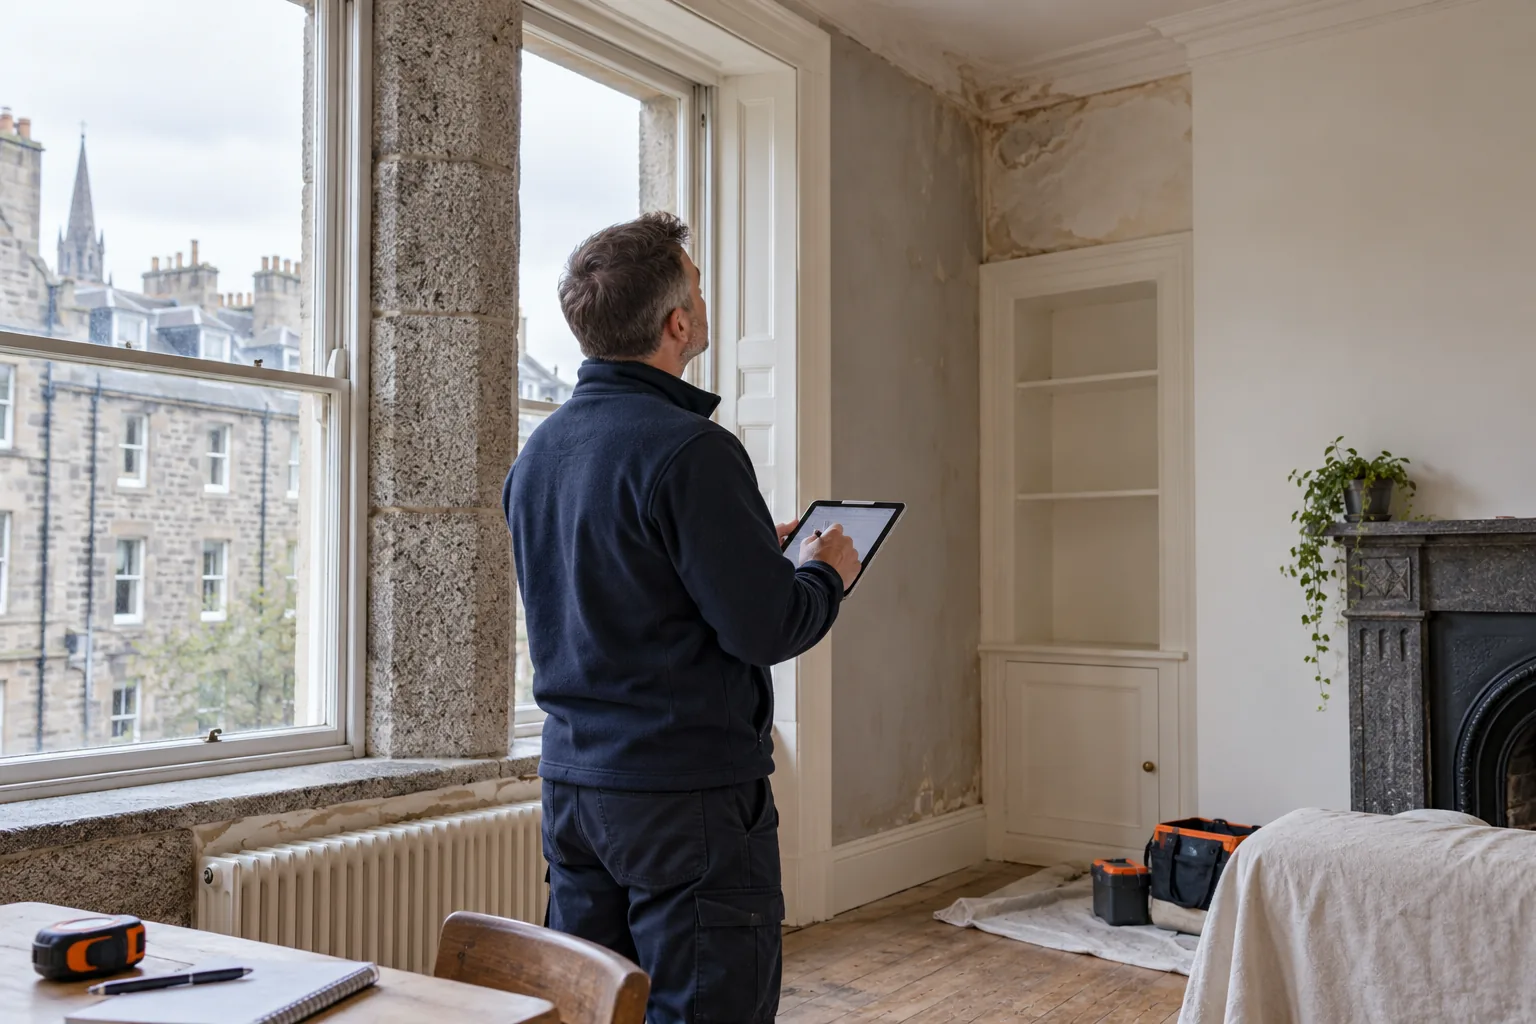
A property assessment can provide evidence for a repair scope; the insurer still makes its own cover decision.
Identify The Question You Need Help With
Try to describe the point that is holding the claim up. Perhaps the insurer has asked for information you do not understand. Alternatively, a proposed repair allowance may be difficult to reconcile with the contractor’s scope.
Give the adviser the relevant correspondence rather than only a summary of the disagreement. Highlight the decision, the reason given and the response you are seeking. This helps an initial conversation stay focused on the actual issue.
Consider How Practical Claim Support May Help
Depending on the agreed appointment, ILA may review policy wording and evidence, organise claim information and communicate with the insurer. It may also assist with settlement discussions. Its guide to the insurance claim process explains the stages of involvement.
For example, if a room appears absent from a repair allowance, the useful next step may be to compare the inspection evidence with the written scope. A clearer explanation may resolve a misunderstanding; further evidence may be needed. Neither possibility establishes cover automatically.
Repair planning and insurance claim representation are different roles, even when the same property needs both.
Clarify Fees Before Making An Appointment
ILA offers a free initial conversation. That does not mean the full claims service is necessarily free. Its published general fee is 10% plus VAT of the overall settlement; confirm the calculation and terms for your own claim.
ILA also describes contractor arrangements that may cover its fee for the relevant reinstatement work. Ask which work and settlement elements are included, what you would pay directly and what happens if you choose another contractor. Request the proposed terms in writing before deciding. Check ILA’s current service and fee information.
Keep Claim Advice Separate From The Repair Contract
The Callout Network helps connect customers with practical restoration and repair services. ILA’s claim representation is a separate service, agreed directly with ILA. A repair quotation does not determine your insurance entitlement.
Before a discussion, gather the policy, claim reference, key correspondence, photographs and available quotations. Ask who would handle the case and what they propose to do. Outcomes and timescales depend on the circumstances, evidence and policy wording. To explore whether support is suitable, contact ILA for free initial claim advice.